The debate over reducing mortgage credit reporting costs has taken an interesting turn.
While the Federal Housing Finance Agency (FHFA) continues to consider replacing mandatory three-bureau reporting with two-bureau or potentially single-bureau reporting, the credit information industry is beginning to disclose what the proposed changes could actually mean.
The emerging question is whether eliminating one credit bureau report would deliver meaningful savings without weakening mortgage credit-risk assessment.
A closer look at the costs
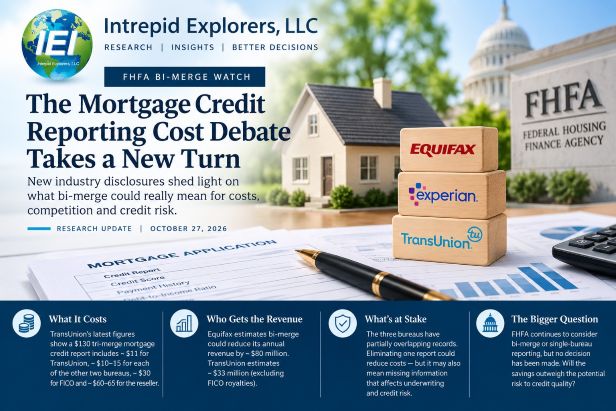
In its October 27 third-quarter earnings presentation, TransUnion provided an illustrative breakdown of a $130 tri-merge mortgage credit report.
According to the company’s estimates, TransUnion receives approximately $11, the other two bureaus receive roughly $10–15 each, FICO accounts for approximately $30, and the reseller receives approximately $60–65.
These figures are illustrative, not independently established industry averages. Nevertheless, they suggest that eliminating one bureau would remove only one component of the total transaction cost.
Meanwhile, all three national credit bureaus have introduced more flexible mortgage information products designed to reduce early-stage application expenses. FICO and VantageScore are also competing on pricing and scoring-model choice.
The industry is responding commercially even before the regulator reaches a final decision.
What is at stake for the credit bureaus?
TransUnion estimates that universal adoption of bi-merge for Fannie Mae and Freddie Mac loans could reduce its annual revenue by approximately $33 million, excluding FICO royalties.
Equifax previously estimated approximately $80 million in potential annual revenue exposure.
These are hypothetical estimates based on company-specific assumptions, not forecasts of actual losses. They demonstrate that the financial consequences differ among the participants.
The information-quality question
The three nationwide credit bureaus maintain overlapping but not necessarily identical consumer records.
A borrower may have an obligation reported to one bureau but not another. Credit scores may differ because of variations in the underlying information.
Consequently, eliminating one report could change the information available to mortgage underwriters.
But the opposite argument also deserves consideration. If two reports produce materially equivalent risk assessments for certain borrowers, requiring a third report may impose unnecessary costs.
What is missing is independently validated evidence comparing the savings with the consequences for underwriting accuracy, borrower eligibility, loan pricing and subsequent credit performance.
What should FHFA establish?
Before changing the reporting requirements, several questions deserve answers.
Who selects the bureaus? What safeguards prevent selective reporting? How will differences in bureau coverage be assessed? And will the resulting savings reach mortgage borrowers?
FHFA has not announced a final implementation decision.
The latest industry disclosures provide useful information about the economics of credit reporting. They do not yet settle the more important question of credit risk.
Reducing the cost of information is desirable. Reducing the quality of information could prove considerably more expensive.
Intrepid Explorers will continue monitoring FHFA’s decisions, industry responses and the evidence supporting proposed changes to mortgage credit reporting.
 Sources: Recent press releases from the industry, IEI monitoring supported by ChatGPT
TransUnion Third Quarter Results
TransUnion Third Quarter Investors Presentation